Should I renew or refinance my mortgage_
Christine MacPherson • March 31, 2025

Should I renew or refinance my mortgage? 

Millions of Canadians are reaching the end of their mortgage term, eager to secure the best possible rate. While many focus on renewing their existing mortgage, they may overlook the possibility of refinancing—a decision that could make a big difference in their financial picture.


What’s the Difference Between Renewal and Refinance?

  • Renewal:
    At the end of your mortgage term (commonly 5 years), you need to “renew” your loan to keep it active. When you renew, your mortgage balance and amortization period (the total time you have to pay it off) stay the same. You can renegotiate your interest rate, but you can’t borrow additional funds or change the original loan amount.


    Example. You bought a home in June 2020 and had a mortgage of $400,000. After a 5-year term at 1.70%, your outstanding mortgage balance will be around $332,939.71, assuming you haven’t made any extra payments. At this point, you’ll need to renegotiate a new interest rate and choose a new term based on your remaining balance.

  • Refinance:
    Refinancing allows you to restructure your mortgage. You can change the loan amount, extend the amortization period, and often access your home’s equity. This flexibility gives you the option to lower monthly payments, consolidate debt, or free up cash for other purposes like renovations or investing.


    Example: Say your home’s value has grown significantly since you first purchased it. Through refinancing, you could borrow more against that increased equity, giving you funds to complete a kitchen renovation, start a small business, or pay off higher-interest debts.


The Impact of Rising Rates

If you locked in a 1.70% fixed rate five years ago, today’s rates—often over 4.50%—may feel like a big leap. Simply renewing might leave you with a payment shock. Refinancing, however, gives you the ability to adjust your monthly obligations, even as rates rise, by stretching out your amortization or accessing equity for financial goals.
A Side-by-Side Comparison (Markdown Table)


Below is a comparison of a $400,000 mortgage at a 1.70% interest rate (renewal scenario) versus refinancing to a longer amortization period with a higher rate:
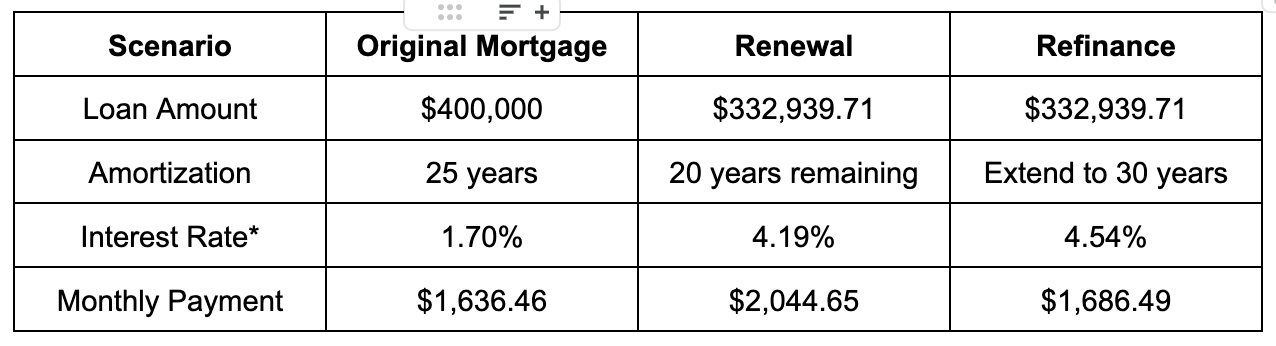
*Rates are for illustrative purposes only. This is not a commitment to lend, pre-approval or approval. OAC, E&O. 


Note: The monthly payment in the refinance scenario is higher due to the higher rate, but stretching out the amortization period can still offer savings compared to shorter-term loans.


Simplifying the Terminology

  • Amortization Period:
    This refers to the total length of time you have to fully pay off your mortgage. For example, a 25-year amortization means your mortgage is structured to be paid in full over 25 years. Choosing a shorter amortization period typically results in higher monthly payments, but you’ll pay less interest overall. A longer amortization period, such as 30 years, reduces your monthly payment but increases the total interest paid over the life of the loan.
  • Term:
    The term is the length of your current mortgage agreement with the lender—commonly 1 to 5 years in Canada. At the end of this term, you need to renew or refinance your mortgage for another term at current interest rates and conditions. While the amortization period stays the same, the term allows for adjustments to the rate and sometimes the type of mortgage you have.
  • Equity:
    Equity is the portion of your home that you truly own, calculated by subtracting the outstanding mortgage balance from your home’s current market value. For example, if your home is worth $600,000 and you owe $400,000 on your mortgage, you have $200,000 in equity. Refinancing can enable you to tap into this equity for expenses like home renovations, debt consolidation, or investment opportunities.
  • Payment Shock:
    This occurs when your mortgage term ends and you’re faced with significantly higher interest rates. The resulting increase in your monthly payment can come as an unpleasant surprise and impact your budget.
In Summary


When faced with renewal, don’t just look at the rate. Consider your overall financial goals. Do you need to borrow additional funds? Are you trying to reduce monthly payments? A refinance may give you more flexibility and options than simply renewing. By understanding the differences and terminology, you can make a well-informed decision that best fits your long-term financial plan.

If you’re unsure which option is right for you, let’s connect. I can help you understand your choices, find the best rates, and create a mortgage strategy tailored to your needs. Reach out today to explore what’s possible!

SHARE THIS ARTICLE
RECENT POSTS

By Christina MacPherson August 20, 2026
Have you noticed how complicated buying real estate has become lately? Whether you are a seasoned homeowner looking to upgrade, a strategic investor expanding your portfolio, or someone finally ready to purchase a beautiful vacation property, navigating the modern lending landscape is no simple task. As a dedicated mortgage professional right here in Edmonton and Calgary, I see these exact challenges firsthand every single day. Recent data confirms what I have been noticing in my office for months. A brand new July 2026 survey from Mortgage Professionals Canada reveals a massive shift in how people secure their financing. A staggering 38 percent of all buyers, and a massive 48 percent of new buyers, are turning their backs on traditional bank branches and working directly with independent brokers instead. Let us explore exactly why this profound shift is happening across the country and how it directly impacts your next real estate move in Edmonton and Calgary. The Numbers Speak For Themselves: A Shift In Trust We all want the absolute best possible deal when we sign a contract. But securing the lowest advertised rate is no longer the only piece of the puzzle. The comprehensive July 2026 survey highlights that while competitive pricing remains critical, modern buyers are heavily prioritizing expert advice, tailored lender choices, and comprehensive guidance through a notoriously complex process. New buyers in particular are feeling the intense pressure of the current market, trying to secure their financial future while balancing strict affordability rules and stress tests. Here is a clear breakdown of why modern buyers are making the switch to brokers, according to the freshly released data. When you look closely at these survey numbers, the reality becomes crystal clear. Buyers in Edmonton and Calgary are completely tired of a one size fits all approach to their finances. They actively want customized advice that helps them increase their purchasing power and structure their household debt responsibly. They want a dedicated advocate who will sit down, listen to their unique goals, and craft a personalized financial roadmap. Beyond The Lowest Rate: Why Advice Matters Most Right Now The days of blindly walking into your local bank branch and simply accepting whatever terms they offer are completely gone. Today, making the wrong choice on your lending term can end up costing you thousands of dollars in unnecessary interest or severe penalty fees. The recent survey pointed out that fixed rate products are still the dominant choice, currently held by 70 percent of mortgage holders. However, 26 percent of people now have a variable rate product, which represents a noticeable and significant increase from previous years. Why does this specific statistic matter to you? Because choosing between a fixed and variable product requires a deep understanding of complex economic trends and your own personal risk tolerance. If you currently hold a variable rate, you absolutely have to know if your monthly payment fluctuates directly with the prime rate (which 55 percent of variable holders currently experience) or if you have a rigidly set payment that merely adjusts the principal portion (which applies to the remaining 45 percent). Navigating these critical nuances is exactly why you need a licensed professional in your corner. I take the time to deeply evaluate your specific financial goals, whether you are buying your very first property or selling an existing one to downsize comfortably. Saving For The Down Payment: Are You Using The Right Tools?
By Christine MacPherson June 18, 2026
The real estate landscape has shifted dramatically. For years, the play for many real estate investors was simple: buy a condo or a townhouse in a major urban center like Toronto or Vancouver, hold onto it, and watch the equity grow. Cash flow was an afterthought because rapid price appreciation did the heavy lifting. As we navigate through the economic realities, that old playbook is no longer working. Elevated interest rates and massive carrying costs mean that high-priced urban properties are frequently draining cash every month. Rents, while high, simply cannot keep pace with soaring mortgage payments in major metro cores. Because of this, savvy investors are changing their approach. They are moving away from major metropolitan centers and redirecting their capital toward secondary markets where positive cash flow is actually achievable from day one. As an experienced professional working directly with buyers right here in Edmonton and Calgary, I am watching this transition happen in real time. Investors are no longer willing to subsidize a tenant's housing cost in hopes of future appreciation. Instead, they want resilient assets that increase their net monthly income immediately. Why Major Urban Hubs Are Losing Traction The reality of investing in a major city center today comes down to simple math. When property acquisition costs are exceptionally high, the rent-to-price ratio becomes compressed. This creates a scenario where an investor must put down a massive down payment just to break even on the monthly expenses. Several distinct factors are driving this decline in major hub traction: Stretched Price-to-Income Ratios: Local buyers and renters in large metropolitan areas are hitting affordability ceilings, limiting how much further rents can realistically rise. Squeezed Cap Rates: High entry prices mean net operating incomes represent a much lower percentage of the overall property value. Stalled Pre-Construction Markets: The condo sector has experienced a notable correction, causing investors to look for existing, cash-flowing inventory rather than waiting years for completions. For individuals residing or looking to invest in Edmonton and Calgary, the local market offers a refreshing alternative to the congested, low-yield environments of Canada's largest cities. Local economic stability and reasonable entry points provide a perfect environment for building true real estate wealth. The Math Behind the Migration To understand why the secondary market pivot is accelerating, it helps to analyze the fundamental investment metrics. Experienced investors focus heavily on Gross Rental Yield and the rent-to-price ratio to compare the viability of different regions. Average Entry Price - Major Urban Hub (e.g., GTA Core): High ($750,000+) vs. Secondary Market: Moderate ($350,000 to $500,000). Average Gross Rental Yield - Major Urban Hub: Low (3.5% to 4.5%) vs. Secondary Market: High (6.0% to 7.5%). Rent-to-Price Ratio - Major Urban Hub: Unfavorable (low monthly return relative to cost) vs. Secondary Market: Favorable (strong monthly return relative to cost). Cash Flow Status - Major Urban Hub: Often negative or break-even vs. Secondary Market: Frequently positive from day one. Primary Growth Driver - Major Urban Hub: Speculative appreciation vs. Secondary Market: Strong local employment and in-migration. The Core Advantages of Secondary Markets When capital moves out of the largest cities, it flows directly into regional hubs that possess strong underlying fundamentals. These secondary markets are experiencing steady population growth due to interprovincial migration and individuals searching for a more affordable cost of living. Increased Cash Flow Potential The primary motivator for this pivot is positive cash flow. In a secondary market, the relationship between the purchase price of a home and the going rental rate is much healthier. Because your initial mortgage amount is lower, your monthly debt servicing costs are manageable, leaving a healthy surplus of rental income after all expenses, property taxes, and maintenance costs are paid. Strong Rental Demand and Low Vacancy Rates Many secondary markets are facing acute housing shortages. Because fewer large-scale high-rise developments are built in these areas, the existing supply of rental housing is highly sought after. Low vacancy rates ensure that landlords can secure reliable, high-quality tenants quickly, minimizing the risk of costly vacant months. Choosing the Right Property Type for Maximum Returns To truly capitalize on secondary market dynamics, smart investors are focusing on specific property designs that maximize revenue streams from a single piece of land. The Missing Middle: Duplexes, triplexes, and townhomes are highly popular because they offer multiple rental units under one structural roof, diversifying your income risk. Properties with Legal Suites: Single-family homes that feature fully permitted basement suites or garden suites allow you to collect two separate rent checks while maintaining a lower entry price point than a commercial multi-family building. If you are a homeowner looking to leverage your existing equity, a first-time buyer wanting to start with a smart investment, or an investor seeking to restructure your current portfolio, identifying these high-yield opportunities is essential. Moving your focus to regional markets allows you to build a sustainable, self-sustaining real estate portfolio that stands up to economic volatility. Are you ready to explore how secondary market opportunities can increase your monthly cash flow? Contact our team today to review your financing options and establish a customized strategy tailored to your long-term wealth goals.  Phone: 403-968-2784 Email: christine@flaremortgagegroup.com
Show More